Alerts, Insurance, and Protecting Your Property
Two houses stand on the same street after a hurricane. One owner spent an afternoon documenting belongings and checking policy coverage the month before. The other did not. The first files a claim with photos and receipts and a Proof of Loss ready. The second spends a year reconstructing their life from memory for an adjuster who needs evidence. FEMA’s guide calls this section “Take Action”, and it is where preparedness becomes financial survival. Nearly 25 percent of all flood insurance claims come from outside the high-risk flood area, which tells you how well intuition works for insuring a home.
Disclaimer: The information provided in this article is for general informational and educational purposes only. It is not intended as, and should not be considered, legal or financial advice. Consult your insurance agent and qualified professionals for your specific situation.
The Readiness Audit
If your home were damaged tonight, could you prove what you owned and what the policy covers?
- Green: You are subscribed to local alerts, you know which perils your policy covers, and a documented home inventory exists outside the house.
- Yellow: You have insurance but have never read what it covers, and your inventory is a mental list.
- Red: You are unsure whether you even have coverage for the most likely hazard in your area.
If you are Yellow or Red, execute Phase 1 immediately.
Phase 1: Keep Informed
Goal: Build the alert layer that reaches everyone.
The guide’s instruction is to learn which alert and warning systems exist for the places you spend time (work, home, school, away) and subscribe to them. Officials can then send text or email messages about local emergencies, and some systems have mobile apps. The FEMA app offers local threat notifications. Check that your mobile devices can receive Wireless Emergency Alerts (WEAs). Workplaces, schools, and community or faith groups may run their own opt-in systems. Then make a list of every alert system available to you, and make sure everyone in the household receives the alerts as part of your communication plan. The guide adds an inclusion note: assistive communication devices help people with disabilities and others with access and functional needs receive forecasts, warnings, and emergency messages.
The Takeaway: Alerts are the cheap end of preparedness: a subscription and a checklist item. They only work if every household member is wired in, not just the most organized adult.
Phase 2: Insurance and the Home Inventory
Goal: Know what is covered and prove what you own.
Insurance is the difference between a quick recovery and years of financial challenges. Homeowners and renters policies typically cover dwelling, other structures (garages, decks, fences), personal property, loss-of-use payments if you must move temporarily, personal liability, medical protection for injuries on your property, and accidental damage to others’ property. Renters, take note: landlords often require proof of renter’s insurance at lease signing, and business owners need commercial coverage for property and employees. Manufactured homes, condos, and farms use special policies, and mortgage lenders set minimum coverage requirements.
Policies pay by peril, the named cause of loss like fire or theft. Basic property policies may not cover flooding, wind, earthquakes, terrorism, or pollution. Flood coverage comes through the National Flood Insurance Program, and earthquake, terrorism, and pollution coverage can be purchased separately or as add-ons. Flooding is the most common and costly disaster in the U.S., Federally-backed mortgages in high-risk areas require flood insurance, and there is usually a 30-day waiting period between purchase and coverage, so do not delay. Standard policies do not cover flooding, full stop.
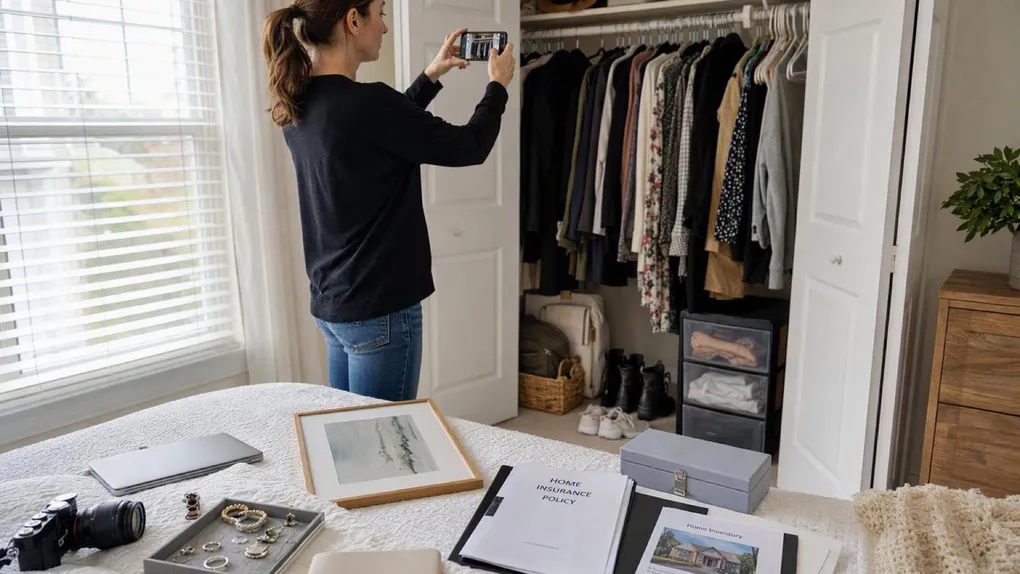
Document the property: photograph or video your belongings with descriptions including year, make, and model. Shoot inside and outside, including closet and cabinet interiors. Get appraisals for high-value items. Keep the inventory on a portable drive, in cloud storage, electronically, or on paper, somewhere away from the home that survives the disaster.
The Takeaway: The policy is a contract you must be able to quote, and the inventory is the evidence. Both live outside the house in your head, your cloud, or your safe deposit box, because the disaster that damages the house destroys whatever stayed inside it.
Phase 3: Mitigation and the One-Year Plan
Goal: Harden the property and put the plan on a calendar.
Mitigation makes the potential impact less severe. Trim trees away from the home, install working shutters, anchor manufactured homes, build a tornado safe room. Most structural mitigation needs professionals, but do-it-yourself techniques exist. Building or renovating is the moment to apply it: find out whether the site floods, faces storm surge, sits on steep slopes, is exposed to ground shaking, or is close to hazardous facilities, then build to or beyond code, including high-wind standards. Existing homes can upgrade windows, doors, and garage doors to windborne-debris standards and retrofit safe rooms. Tell your insurance agent about mitigation measures, because they may qualify you for discounts.
Then practice, on a schedule. The guide’s recurring actions: test evacuation and shelter plans, test the communication plan, refresh emergency supplies at least every six months, hold an emergency response drill, keep critical documents safe and updated, review the inventory as belongings change, and have an insurance checkup. It even proposes a 12-month timeline: CPR and first aid training in month 1, the customized family plan in month 2, financial savings in month 3, evacuation drills in month 4, testing the communication plan in month 5, safeguarding documents in month 6, planning with neighbors in month 7, home safety projects in month 8, household briefing in month 9, supplies in month 10, community involvement in month 11, and insuring and documenting property in month 12.
The Takeaway: One year, twelve modest moves, and the household goes from unprepared to audit-green. The calendar is the trick: each month has exactly one job.
The Essential Kit Checklist
- The Alert Stack: Local alert systems subscribed for every household member, WEAs enabled, FEMA app installed.
- The Policy Read: A coverage review completed, noting perils covered and excluded, with flood insurance purchased if any flood risk exists.
- The Inventory: Photos or video of belongings and home interior and exterior, with descriptions, stored away from the house.
- The Mitigation List: Trees trimmed, shutters working, upgrades noted to your agent for possible discounts.
- The Practice Calendar: The recurring test schedule or the 12-month timeline, whichever fits your starting point.
Scenario Planner (Contingencies)
“We are not in a flood zone, so flood insurance is a scam.” The trap: risk maps are about probability, not possibility, and the guide states nearly 25 percent of flood claims come from outside high-risk areas. The fix: price the policy, remember the 30-day waiting period kills last-minute buying, and compare that cost to one flooded basement.
“Our inventory is three years old.” The trap: an outdated inventory leaves every purchase since the last review uninsured and undocumented. The fix: the guide says review the inventory as belongings change, so tie the update to the six-month supply rotation and it becomes a 20-minute habit.
Next Steps
- Re-run the Readiness Audit. Scroll back to the top, answer the three questions honestly, and close whichever gap they reveal before you close this tab.
- Print the checklist. The kit list above only works if it exists when the power is out, so paper beats apps here.
- Fold it into the family plan. A prepared household beats prepared person, so put these steps in front of everyone who shares your roof.
Next: Read Recovering From a Disaster the Right Way for the guide’s post-event playbook, from first inspection to fraud protection.
Adapted from Federal Emergency Management Agency - Are You Ready? An In-Depth Guide to Citizen Preparedness (public domain). Read the original: Are You Ready? An In-Depth Guide to Citizen Preparedness.